Update: From Instant Depth To Economic Liquidation Capacity
The original note ended with a question: should clearance for redeemable collateral be judged only against instant routed depth, or against capacity over a stated horizon? I extended the wstETH case from a capacity test into a liquidator balance-sheet sensitivity.
The strict result is unchanged. A $256.52 million wstETH sale remains far above the $2.73 million that current routed DEX quotes clear instantly within the 6% bonus. That test is still FAIL and excludes redemption, CEX, and OTC liquidity.
The extension asks a different question. Suppose a liquidator repays about $242 million at time zero, receives the collateral, hedges ETH/USD, and warehouses the position while exiting through DEX liquidity or primary redemption. Can the liquidation bonus cover recovery losses, funding, hedge carry, and the required return on capital?
The route optimizer selects one total DEX/redemption allocation that maximizes economic profit, then executes each allocation at its earliest modeled capacity. The published sensitivity uses:
- 10% annual funding and a separate 10% annual capital hurdle;
- 0.10% hedge entry and 2% annual hedge carry;
- a 1% DEX execution-loss ceiling;
- a 24-hour redemption delay and illustrative $25 million/day throughput;
- 4% canonical or oracle-to-recovery loss and zero additional DEX discount.
route                         clear time   economic profit   minimum bonus
quiet DEX only                   30.11d          -$0.66m            6.29%
stressed DEX only               241.88d         -$16.92m           13.49%
optimized DEX + redemption       11.26d           $3.11m            4.66%
At the assumed redemption rate, the optimizer assigns all $256.52 million to redemption. Quiet and stressed blended rows therefore coincide: DEX depth is not decision-relevant once the chosen route avoids it. This is not evidence that a 6% bonus is sufficient in practice. It shows that the conclusion is controlled by the redemption assumption.
That dependence is visible in a correlated stress sensitivity. Halving stressed redemption throughput to $12.5 million/day increases exit time to 21.08 days, reduces economic profit to $2.37 million, and raises the minimum bonus to 4.98%. The optimizer then assigns $5.49 million to DEX and $251.03 million to redemption.
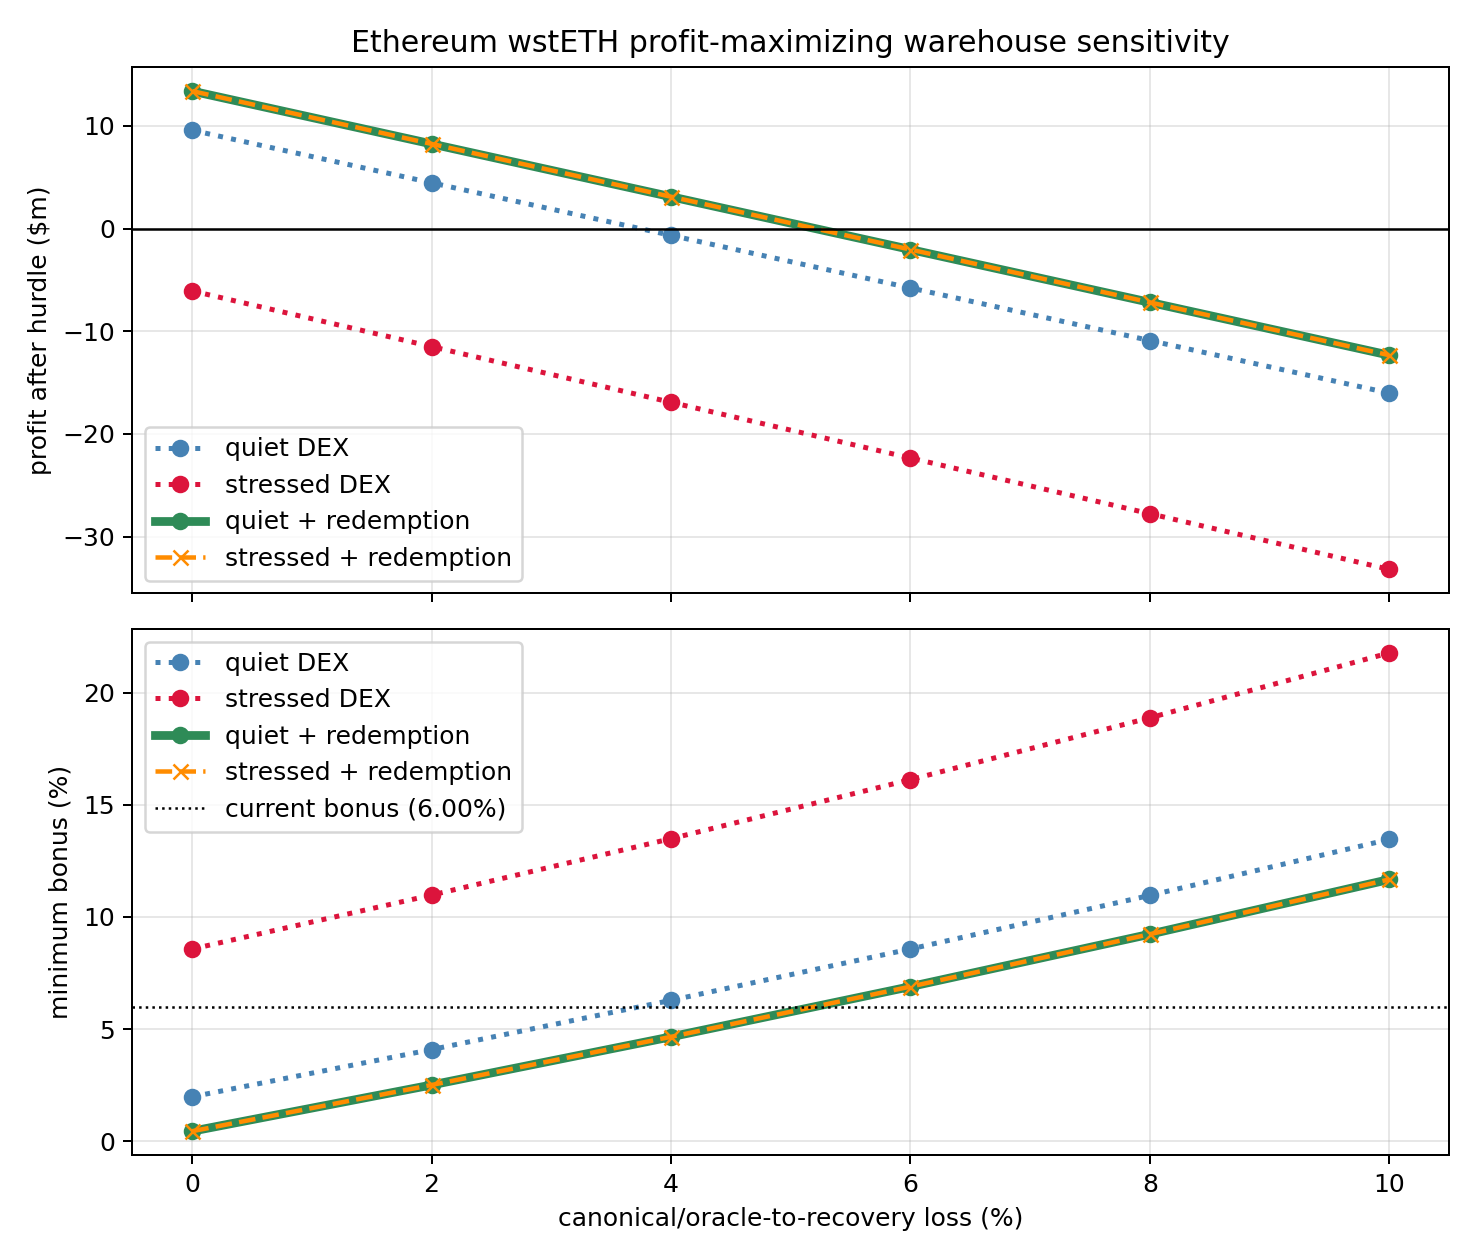
The main limitation is now explicit: $25 million/day is a sensitivity input, not a measured Lido stress-throughput estimate. The model also assumes sufficient full-upfront financing, deterministic future capacity, and a static route split. It does not establish that redemption slots or the required hedge can be secured. These outputs are not a wstETH safety claim or a liquidation-bonus recommendation.
This suggests that two tests may be more informative than forcing one interpretation:
- strict instant clearance against observable routed depth;
- horizon-adjusted economic clearance under explicit funding, canonical-loss, and redemption-throughput stresses.
A governance conclusion should not treat the second test as a pass on an uncalibrated throughput assumption. Its current value is to identify the empirical quantity that controls the answer.
For redeemable collateral, should the Risk Framework supplement instant clearance with a specified exit horizon and stressed primary-redemption throughput, while requiring the liquidation bonus to compensate the liquidator’s capital and recovery risk over that horizon?
Exact results and commands | Run manifest | Model specification
python -m aave_risk_engine.run_liquidator_balance_sheet \
  --snapshot data/snapshots/aave_v3_ethereum_wsteth.json \
  --redemption-usd-per-day 25000000 \
  --canonical-losses 0.04